All Categories
Featured
Strategic Workforce Optimisation for Modern British Firms
Table of Contents
Notes: GDP development is specified as the yearly modification in genuine (inflation-adjusted) GDP in the forecast year compared to the previous year. Joblessness rate is since December for each year. Core inflation is the year-over-year modification in the Consumer Rates Index, leaving out volatile food, energy, alcohol, and tobacco rates, based upon the fourth-quarter average for each year.
Yael Selfin, Vice Chair and Chief Financial Expert, KPMG in the UK, was joined by David Smith, Economics Editor at the Sunday Times and Chris Hearld, Group Handling Partner, KPMG, to explore how families and companies could be impacted and the challenge for the brand-new government of providing development while managing public financial resources.
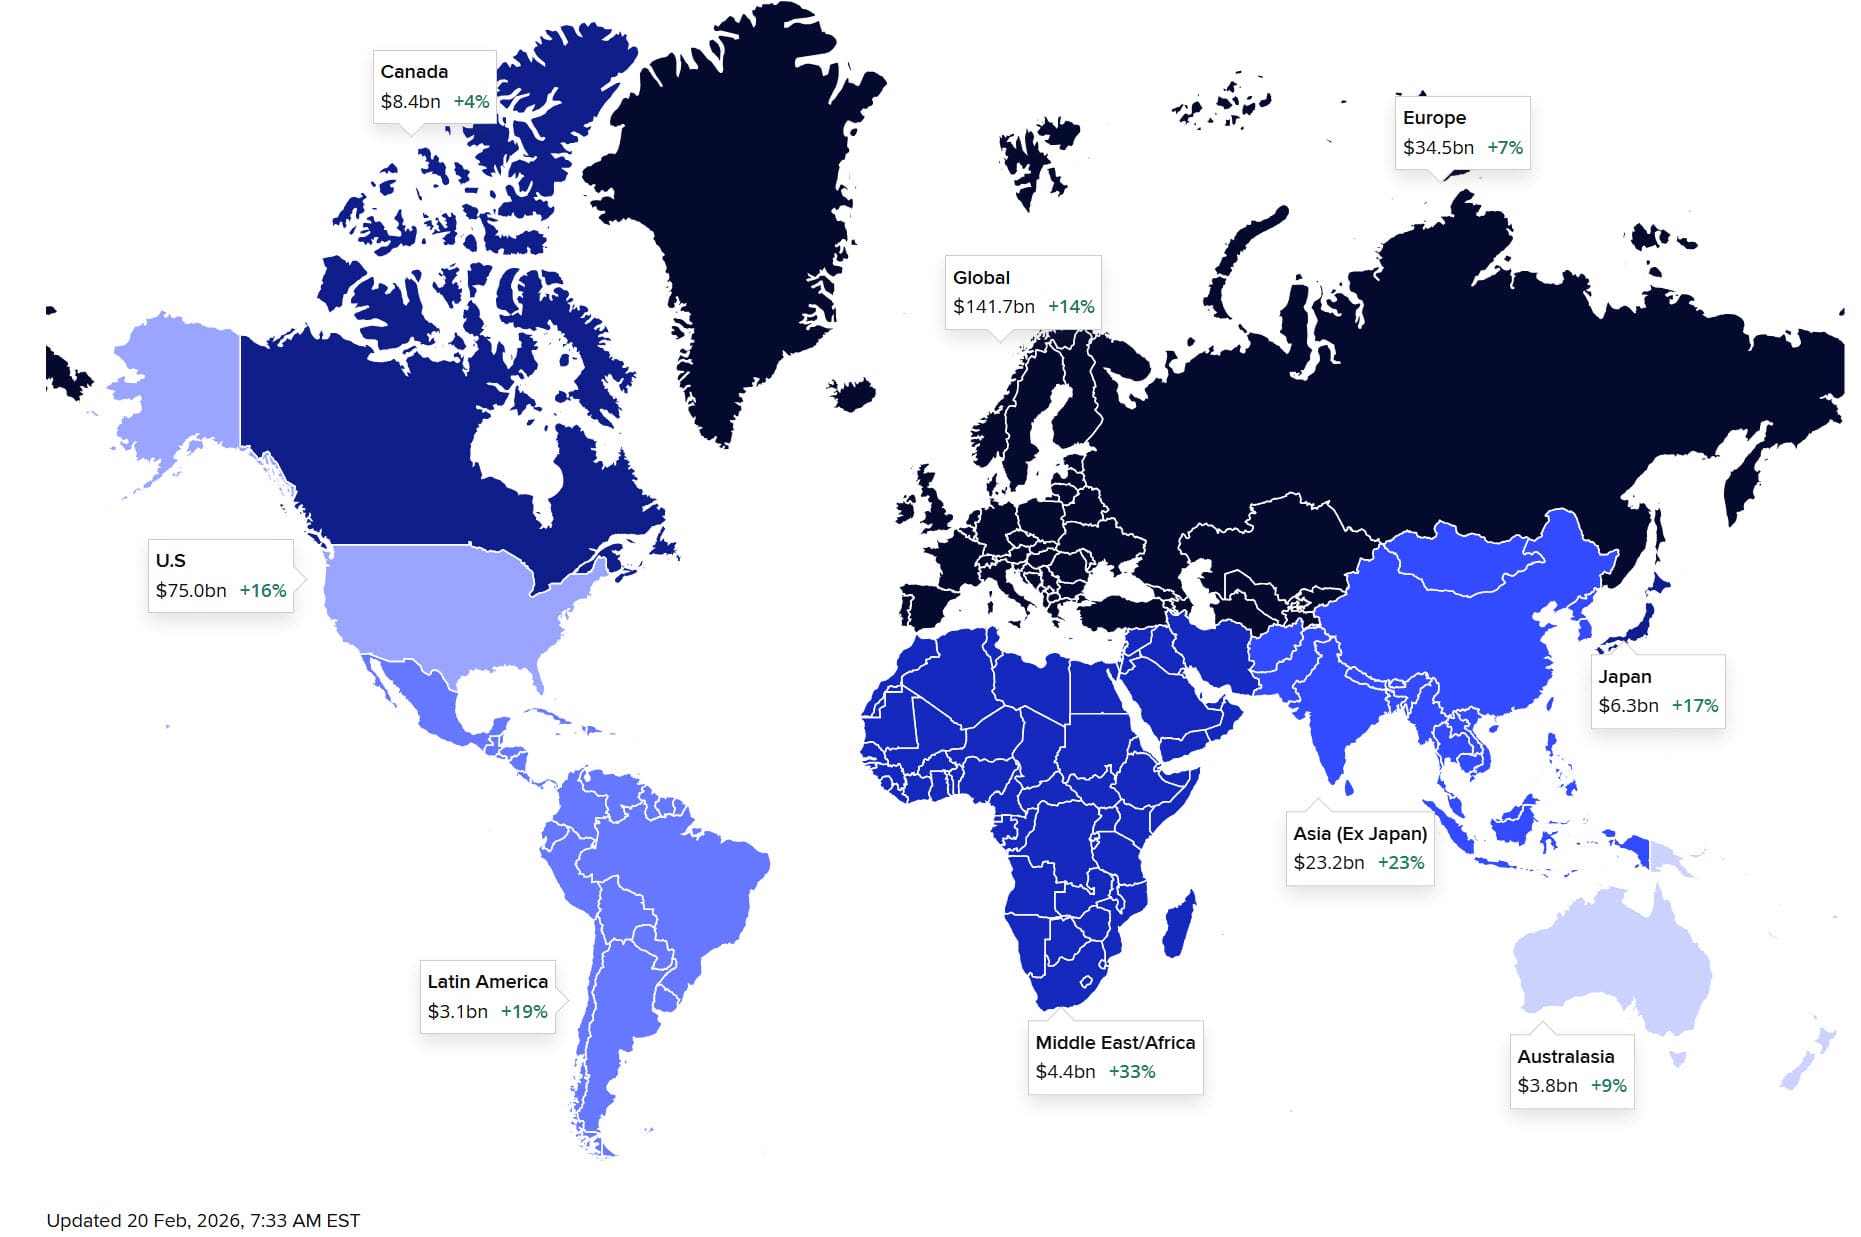
The world economy grew by 3.3 per cent last year, nearly identical to the rates recorded in 2023 and 2024. US growth slowed from 2.8 per cent in 2024 to 2.2 per cent in 2025, as tariffs, tighter immigration policy and raised uncertainty weighed on demand.
Venture Capital Trends for British Expansion Success
China and India preserved fast expansion at 5.0 percent and 7.4 percent respectively. This reflects postponed tariff effects and elevated uncertainty moistening investment. Growth in innovative economies is set to slow to 1.8 percent in 2026 (US 2.3 percent, Euro Area 1.3 percent, Japan 0.8 percent), with emerging markets growing by 4.0 percent (China 4.6 per cent, India 6.5 percent). US CPI inflation (2.7 per cent in December 2025) is anticipated to average 2.6 percent in 2026, showing tariff pass-through and a weaker dollar.
Future Banking Strategies for British Growth Markets
The ECB has held its policy rate at 2 percent and is most likely to maintain this position. Long-term bond yields stay raised, with US 10-year Treasuries around 4.3 percent and Japanese 10-year federal government bond yields increasing greatly to around 2.3 percent, up from 0.3 percent in 2023. Tariff effects are still overcoming, while US actions in Venezuela, tensions over Greenland, and China's export controls on important minerals raise the risks of further interruption.
GDP grew by 0.7 per cent in Q1 as organizations brought forward activity ahead of the April increases in company National Insurance coverage Contributions and the National Living Wage. Development then slowed to 0.2 percent in Q2 and 0.1 per cent in Q3, held back by Budget-related uncertainty and a cyber-attack impacting Jaguar Land Rover.
The near-term outlook is supported by residual financial growth and steady intake growth. Beyond 2027, development should settle somewhat above trend at around 1.3-1.4 percent. Provided current population forecasts, this implies per capita GDP growth staying listed below 1 percent from 2027 onwards, highlighting the UK's persistent performance challenge.
Navigating the UK Enterprise Management Market in 2026
Our main projection is for CPI inflation to average 2.3 per cent in 2026 and to settle around target thereafter. Services inflation (at 4.5 per cent in December) and core inflation (3.2 per cent in December) remain annoyingly elevated, pointing to persistent underlying cost pressure.
Typical profits development was 4.7 per cent in the three months to November 2025. We predict this to slow to around 3.6 percent in 2026 and 3.1 percent in 2027 as rising unemployment reduces workers' bargaining power a small amounts essential for inflation to stay at target on a continual basis.
This shows lingering unpredictability about the outlook and the scars from the recent inflation shock. We anticipate this raised savings ratio to continue, constraining intake development to around 1.0 per cent in 2026 and 1.3 per cent in 2027. With inflation falling and unemployment rising, we expect two more 25 basis point cuts in 2026, bringing the rate to 3.25 per cent by year-endour quote of the long-run neutral rate.
Future Business Funding Projections for British Growth Sectors
On our projection, the existing budget plan is close to balance by 202930, implying no reliable headroomBox C takes a look at distinctions between the OBR's projection and ours. Public financial obligation continues to increase, with the debt-to-GDP ratio approaching 100 per cent by decade-end, restricting the scope for discretionary financial support in future shocks.
By contrast, positive net migration supports financial sustainability by expanding the working-age population and expanding the tax base. Increases in company National Insurance coverage Contributions, significant upratings of the National Living Wage (NLW), and reforms to employment rights have actually raised the limited expense of employing by around 7 per cent in genuine terms for an entry level position.

Latest Posts

Optimizing Workforce Acquisition for UK Business Landscape
Strategic Workforce Optimisation for Modern British Firms
Future UK Industry Trends in 2026